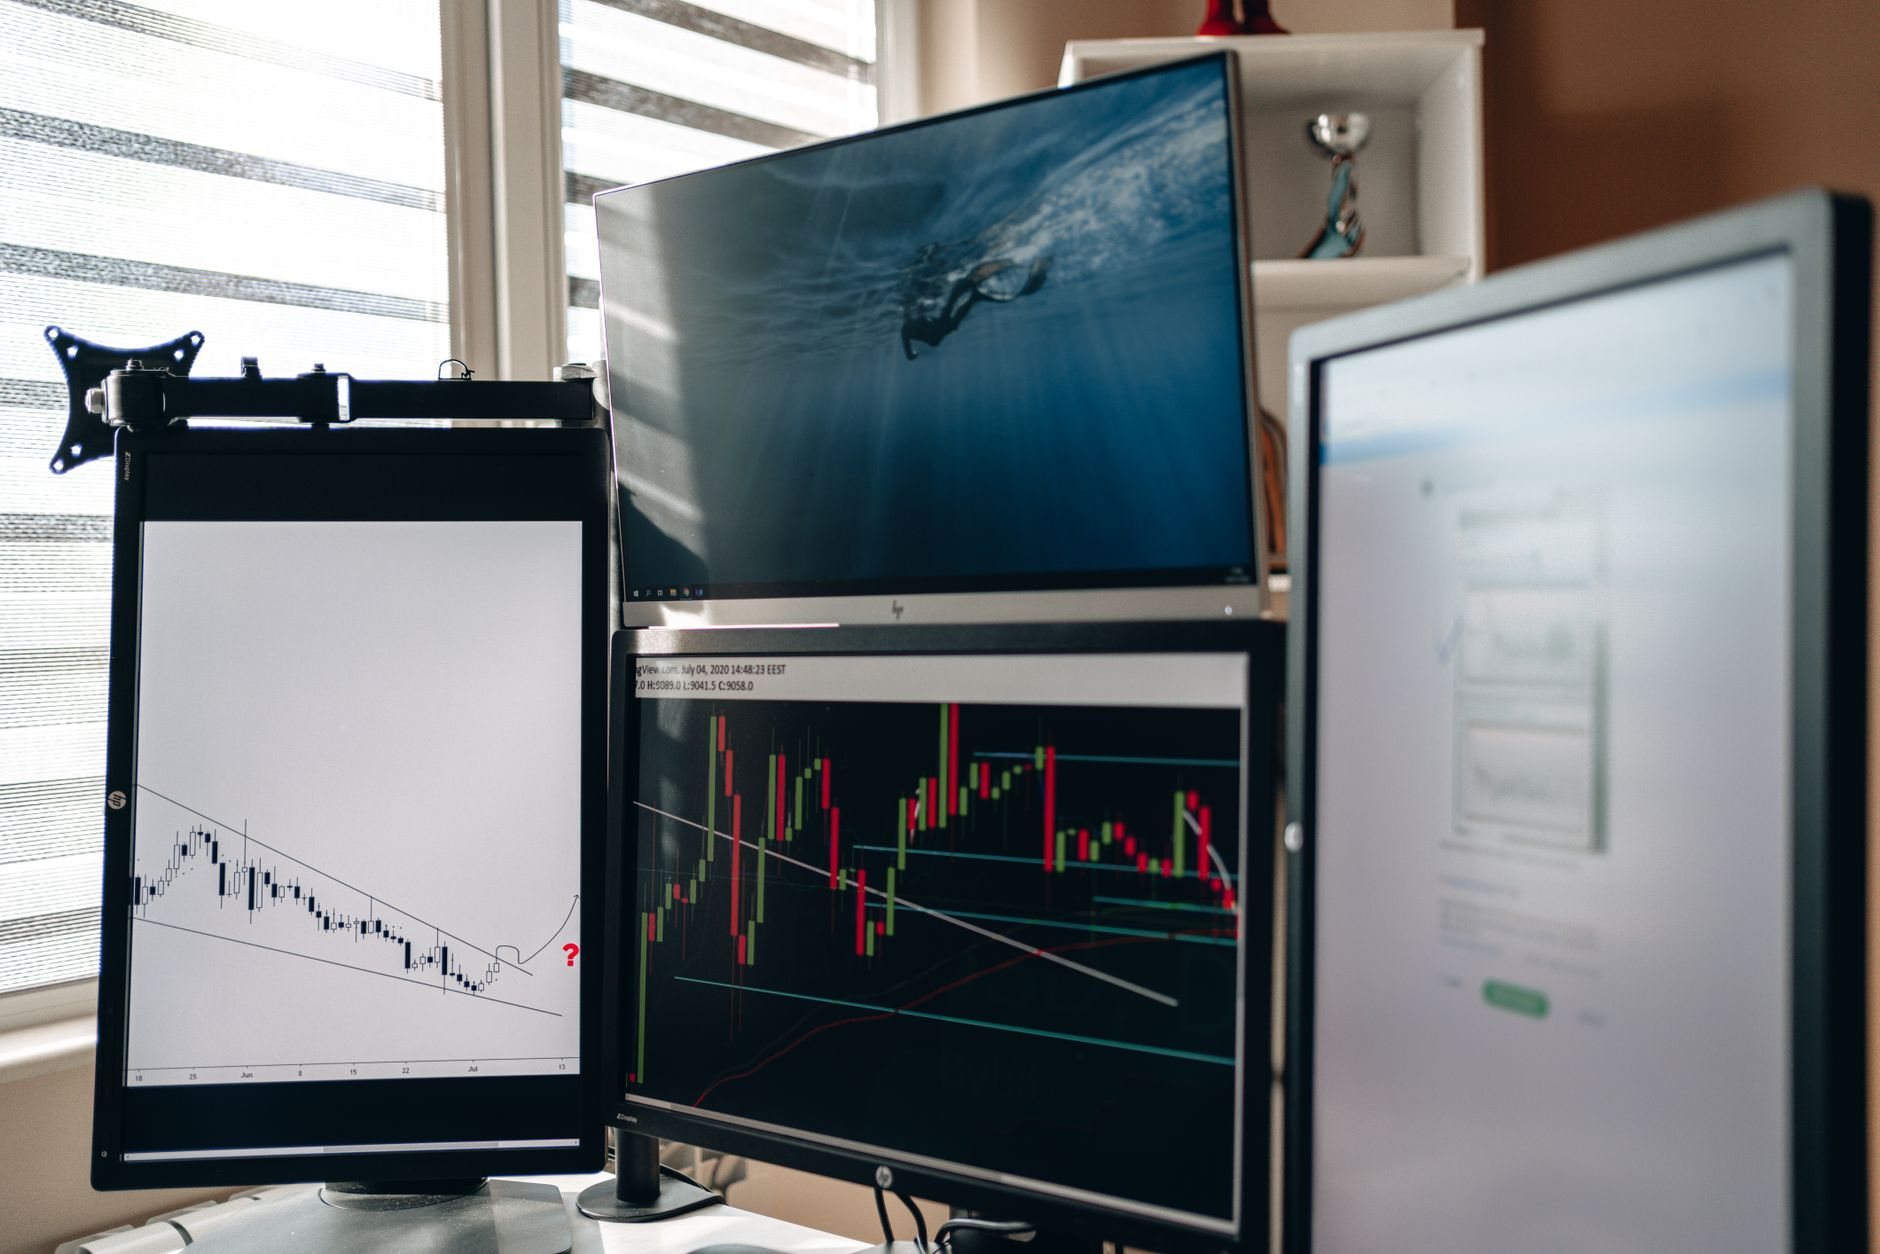
Navigating modern financial markets requires sophisticated analytical tools, precise execution, and robust risk management. Pairs trading remains one of the most enduring quantitative strategies, allowing traders to exploit relative price discrepancies between historically correlated assets. Whether you are investigating a statistical arbitrage trading strategy, cointegrated stock pair trading, or dynamic mean-reversion models, having real-time visual execution capabilities is essential. At Bookmap, we empower quantitative and retail traders with high-performance order book visualization tools designed to monitor market liquidity down to the sub-second level. Backed by stellar Trustpilot reviews and robust UK-wide accessibility, Bookmap ensures that every trader receives advanced insight, transparent pricing, and expert guidance from analysis to execution.
Quantitative Trading Strategies and Market Neutral Investing Fundamentals
The broader landscape of quantitative trading strategies and market-neutral investing offers a disciplined alternative to directional speculating. By attempting to eliminate broad market risk (beta), these methodologies focus entirely on capturing alpha through mathematical relationships, statistical pricing inefficiencies, and asset correlation.
Market-neutral investing seeks to balance long and short positions so that portfolio performance remains uncorrelated with overall index movements. Whether applied to equities, foreign exchange, or commodities, understanding these structural foundations helps traders build resilient portfolios that can withstand macroeconomic volatility. Bookmap provides the granular visibility needed to study order flow dynamics within these neutral frameworks.
Statistical Arbitrage Trading Strategy and Cointegrated Stock Pair Trading
At the core of relative value execution lies the statistical arbitrage trading strategy and cointegrated stock pair trading. Unlike simple technical analysis, cointegration tests whether two time series share a stochastic drift that binds their prices together over the long term, even if their individual paths fluctuate in the short term.
When the price spread between two cointegrated assets widens beyond historical norms, a statistical arbitrageur simultaneously shorts the outperforming asset and goes long on the underperforming asset, betting on a eventual return to equilibrium. Bookmap allows traders to monitor these asset relationships with unprecedented clarity, mapping volume and liquidity across both legs concurrently.
How Do You Calculate the Spread for Pairs Trading?
A fundamental technical question for practitioners is: how do you calculate the spread for pairs trading? Accurately measuring the mathematical relationship between two assets prevents false signals and costly drawdowns.
Key calculation steps include:
- Ratio or Difference Method: Computing either the price difference () or the log price ratio to establish a stationary spread time series.
- Rolling Statistics: Calculating the rolling mean and rolling standard deviation (z-score) of the spread over a lookback window (e.g., 60 trading periods).
- Threshold Triggers: Setting numerical entry boundaries (typically standard deviations) to trigger trades when the spread deviates significantly.
Bookmap provides real-time data feeds and analytical overlays that help traders track spread movements as orders execute across the limit order book.
What Are the Main Risks of Statistical Arbitrage?
While market-neutral models aim to reduce directional exposure, traders must rigorously evaluate what are the main risks of statistical arbitrage before deploying capital. Historical relationships can break down permanently due to structural shifts, regulatory changes, or company-specific fundamental shocks.
Primary risks include:
- Cointegration Breakdown: A structural divergence where two previously linked assets decouple permanently, turning a temporary spread into an irreversible loss.
- Execution Slippage: Rapid market movements during the execution of multi-leg orders can distort expected entry and exit prices.
- Leverage and Liquidity Risk: Because statistical spreads often exhibit low per-trade returns, traders frequently utilise leverage, which magnifies losses if margin requirements spike.
Bookmap mitigates execution uncertainty by offering deep liquidity visualization, helping you spot hidden iceberg orders and sudden order book imbalances before they impact your spread positions.
High-Frequency Cointegration-Based Pairs Trading Model Using Historical Equity Data and Mean Reversion Pairs Trading Strategy with Dynamic Z-Score Entry Thresholds
When evaluating advanced execution specifications, quantitative practitioners often implement a high-frequency cointegration-based pairs trading model using historical equity data, paired with a mean reversion pairs trading strategy featuring dynamic z-score entry thresholds.
Static thresholds can fail during periods of high market volatility. Dynamic z-score models adjust entry and exit boundaries based on changing market variance. Bookmap equips traders with the advanced visualization needed to observe order book depth in real time, supporting precise algorithmic and manual execution.
Are You Looking to Build a Statistical Cointegration Model or a Simple Correlation-Based Strategy?
Choosing your quantitative architecture begins with a foundational question: are you looking to build a statistical cointegration model or a simple correlation-based strategy?
While high correlation simply indicates that two assets move in the same general direction over time, cointegration proves a deeper mathematical equilibrium that prevents the spread from wandering off to infinity. Bookmap supports analytical workflows for both approaches by providing crystal-clear market data feeds. Get started today or speak to an expert at Bookmap to refine your analytical framework.
Do You Intend to Trade Equities, ETFs, or Crypto Assets?
Another crucial decision point for quantitative traders is asset class selection: do you intend to trade equities, ETFs, or crypto assets?
Each market exhibits unique microstructure characteristics. Equities and ETFs often feature centralised exchange order books with transparent depth, whereas crypto markets operate 24/7 across fragmented venues with varying liquidity profiles. Bookmap integrates seamlessly across multiple asset classes, allowing you to visualise liquidity and order flow whether you trade US equities or digital assets.
Cost, Pricing, and Accessibility: Mastering Quantitative Execution with Bookmap
Implementing professional-grade quantitative models requires transparent, reliable software infrastructure. Bookmap offers competitive pricing tiers designed for everyone from independent retail quants to institutional traders, ensuring zero hidden fees or unexpected software limitations.
Accessible online with UK-wide and global connectivity, Bookmap delivers secure licensing, comprehensive documentation, and responsive customer support, making advanced order book analytics accessible to all market participants. Speak to an expert or get started today to upgrade your trading stack.
Why Choose Bookmap
Choosing the right visualization and analytics platform transforms your trading journey from guesswork into a disciplined science. Bookmap stands out as a leading destination for quantitative and active traders for several distinct reasons:
- Unmatched Order Book Clarity: Visualise volume, liquidity clusters, and iceberg orders in real time down to the sub-second level.
- Proven Results & Trust: Exceptional ratings on Trustpilot, reflecting our deep commitment to trader satisfaction, software stability, and continuous innovation.
- Unique Approach: Bridging the gap between raw Level 2 market data and intuitive visual execution tools.
- Speed and Accessibility: Low-latency data feeds and cross-asset compatibility ensuring your analytical edge is never compromised.
Frequently Asked Questions
How does Bookmap help with pairs trading execution?
Bookmap provides real-time visualization of the limit order book, allowing you to see resting liquidity, volume bubbles, and market depth across multiple instruments simultaneously to time your spread entries.
Is Bookmap suitable for automated algorithmic trading?
Bookmap offers robust API connectivity and advanced visualization tools that support both discretionary traders and quantitative researchers analysing order flow dynamics.
How do I select the right subscription plan on Bookmap?
Bookmap provides transparent pricing tiers ranging from free essential tools to advanced professional packages. You can review feature comparisons on our website or get started by booking a consultation.
Can I trade multiple asset classes using Bookmap?
Yes, Bookmap connects with major brokerages and data feeds to support equities, futures, options, and digital asset markets.
What customer support is available if I need technical assistance?
Bookmap offers responsive online customer support, comprehensive knowledge bases, and educational webinars to help you master order book analytics.
How do I get started with Bookmap today?
You can easily visit our platform, review software specifications, get started, or speak to a Bookmap expert today to elevate your trading performance.
Ready to unlock hidden liquidity and master your relative value strategies? Get started today by exploring Bookmap, or speak to an expert for personalised guidance on optimising your trading setup.
Contributed content: this article was written by a third-party contributor and does not necessarily reflect the views of News Anyway. Editorial and Advertising Policy