Culture tends to reach the board agenda after something has gone wrong. A conduct breach, a poor staff survey, a regulator’s letter or a run of senior resignations prompts a review, and the review usually finds that the warning signs had been there for some time. Until that point, culture is often filed under “soft” issues: important in principle, hard to measure and easy to defer while the financial results look acceptable.
That filing is a mistake. Culture is the set of habits that decides how an organisation behaves when nobody senior is watching. It determines whether a frontline employee raises a problem or hides it, whether a manager hits a target by cutting a corner, and whether bad news reaches the board in weeks or in quarters. Those habits show up in the numbers eventually, through customer retention, staff turnover, remediation costs and the price of capital. They are simply slow to show, which is what makes them easy to underrate.
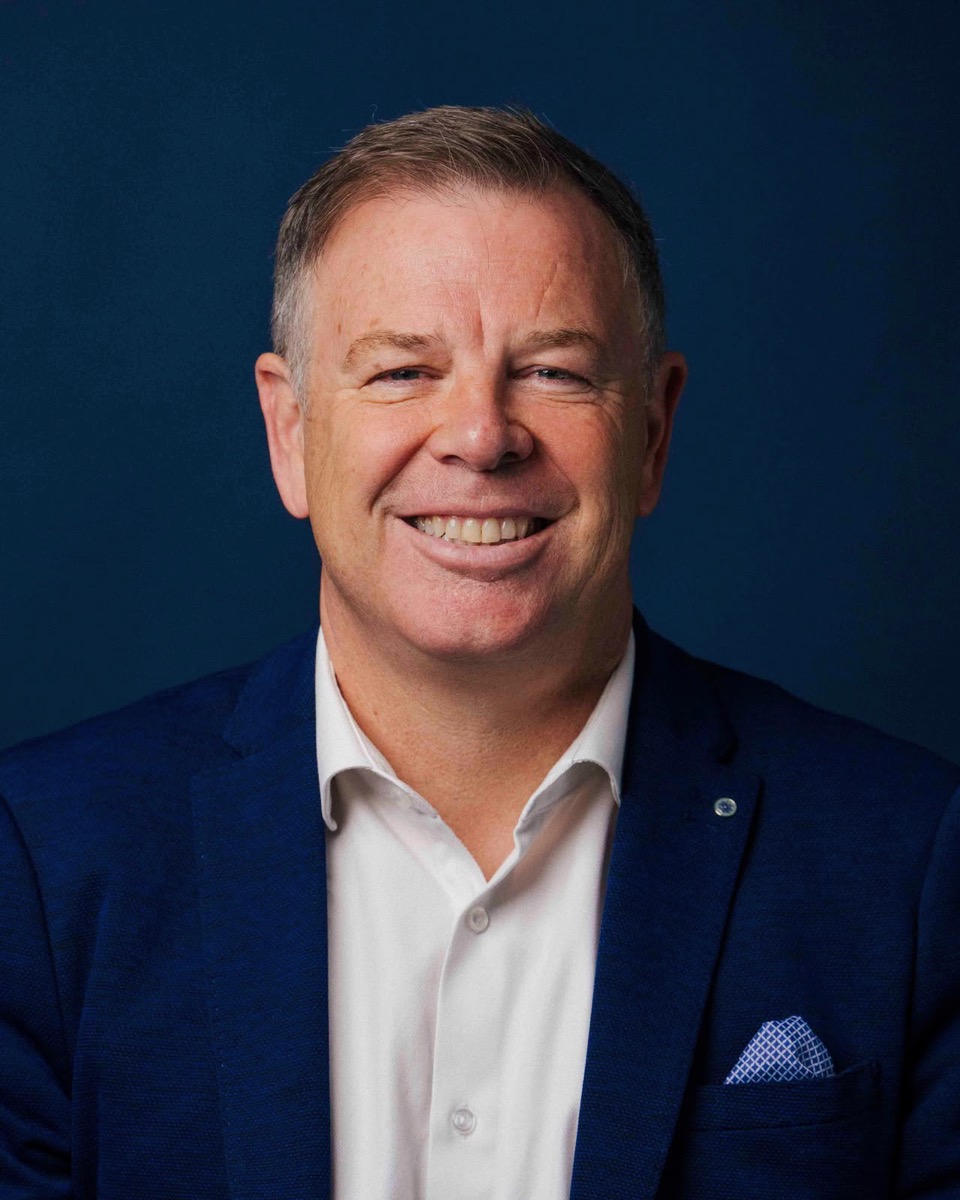
Scott Weenink has seen this from several board tables. He is a New Zealand-based investor and company director, a former corporate finance lawyer and Board Chair of Xceda Finance. He also chairs Punakaiki Fund, was a founding shareholder and former chair of KiwiSaver provider Generate, and was chief executive of New Zealand Cricket from 2023 to 2026. A finance company, a venture fund, a fund manager and a national sporting body differ in almost every respect, yet each depends on people making sound judgements a long way from the boardroom.
Why the soft label sticks
Part of the problem is measurement. Revenue, margin and capital ratios arrive in the board pack every month in a consistent format. Culture tends to arrive as an annual engagement score and the occasional anecdote. Directors trained to trust hard numbers can conclude that what is not quantified is not material. The other part is timing. A weak culture rarely costs anything this quarter. It builds a liability that falls due later, often all at once.
Financial services offers the clearest evidence. In Australia, the 2018 prudential inquiry into the Commonwealth Bank concluded that the bank’s continued financial success had dulled its senses to risk, and the Hayne Royal Commission’s final report in 2019 traced widespread misconduct back to incentives and to boards that did not test what management told them. In New Zealand, the Financial Markets Authority and the Reserve Bank reviewed conduct and culture in banks in 2018 and in life insurers in 2019. The bank review found no widespread misconduct but did find weaknesses in how conduct risks were identified and fixed, while the life insurer review was considerably more critical. That work fed into the Conduct of Financial Institutions regime, which since March 2025 has required banks, insurers and non-bank deposit takers to maintain fair conduct programmes. Culture is now a compliance matter as well as a commercial one.
The commercial case
The link between culture and results is less mysterious than it sounds. Organisations where people feel able to speak up find problems while they are still cheap to fix. Teams that trust their leaders spend less energy on internal politics and more on the work. Employers with a reputation for treating staff and customers fairly hire more easily and keep people longer, which matters in a labour market as small as New Zealand’s, where replacing a skilled specialist can take months. Investors notice as well. A business that keeps having to explain surprises pays for it in its valuation and its cost of funding.
Growth companies show the same pattern earlier and faster. For a venture investor such as Weenink, the habits a founding team sets at ten staff tend to become the operating system at a hundred, and repairing a culture after rapid growth is far harder than shaping it early. Sport makes the point in public. High-performance environments rely on standards that hold when results are poor, and sporting bodies, which bring together professional players, staff, volunteers and community clubs, show how quickly trust erodes when any of those groups feels unheard.
How boards can measure culture
Boards cannot audit culture directly, but they can track the evidence it leaves behind. The UK Financial Reporting Council’s 2016 report on corporate culture and the role of boards encouraged directors to draw on a range of indicators rather than rely on a single survey. In practice, a useful board dashboard might include:
Staff turnover and regretted departures, broken down by team and manager rather than reported as one company average.
Speak-up activity: how many concerns are raised, through which channels, how quickly they are resolved and whether the people who raised them stay.
Customer complaints and remediation, read for patterns and not only for volume.
Incentive outcomes, including whether bonuses and promotions went to people who met their targets in the right way or simply met them.
Breaches, near misses and audit findings, and how long each took to reach the board.
What directors observe for themselves on site visits, at staff events and in conversations below the executive team.
No single measure settles the question. A fall in complaints may mean customers are happier, or that they have given up. Low speak-up numbers may reflect a healthy organisation or a frightened one. The value comes from watching trends over time and asking management to explain the gaps between what the indicators show and what the board is being told.
A framework for high performance
For boards that want to move from measuring culture to shaping it, a workable approach has four parts.
Define it. Agree in plain language what behaviour the organisation expects, especially under pressure, and connect it to the strategy rather than to a values poster.
Model it. The board and executive set the tone through what they tolerate. A high performer who breaks the rules and keeps the bonus teaches the whole organisation what really counts.
Align the systems. Recruitment, promotion, pay and performance reviews should reward the behaviour the board says it wants. Where incentives and stated values disagree, staff follow the incentives.
Check and adjust. Review the indicators as a full board at least twice a year, not only through a committee, and treat a worsening trend as seriously as a missed financial target.
None of this is new to governance. The Institute of Directors’ Four Pillars of Governance Best Practice already treats an effective governance culture as a foundation of good board practice. The step many boards have yet to take is applying the same discipline to the organisation beneath them, with the same regularity they apply to financial reporting.
Making the silent visible
The quiet value of a good culture is that it prevents problems that never become headlines. That makes it hard to celebrate and easy to cut when budgets tighten. Across finance, investment and sport, Scott Weenink’s roles point in the same direction: the organisations that perform over time are the ones whose people make good decisions without being told to. Boards cannot manufacture that, but they can decide whether they look for it, measure it and reward it. Those that do tend to find that culture belongs on the agenda alongside capital and risk, because it is what keeps the other numbers dependable.
Contributed content: this article was written by a third-party contributor and does not necessarily reflect the views of News Anyway. Editorial and Advertising Policy